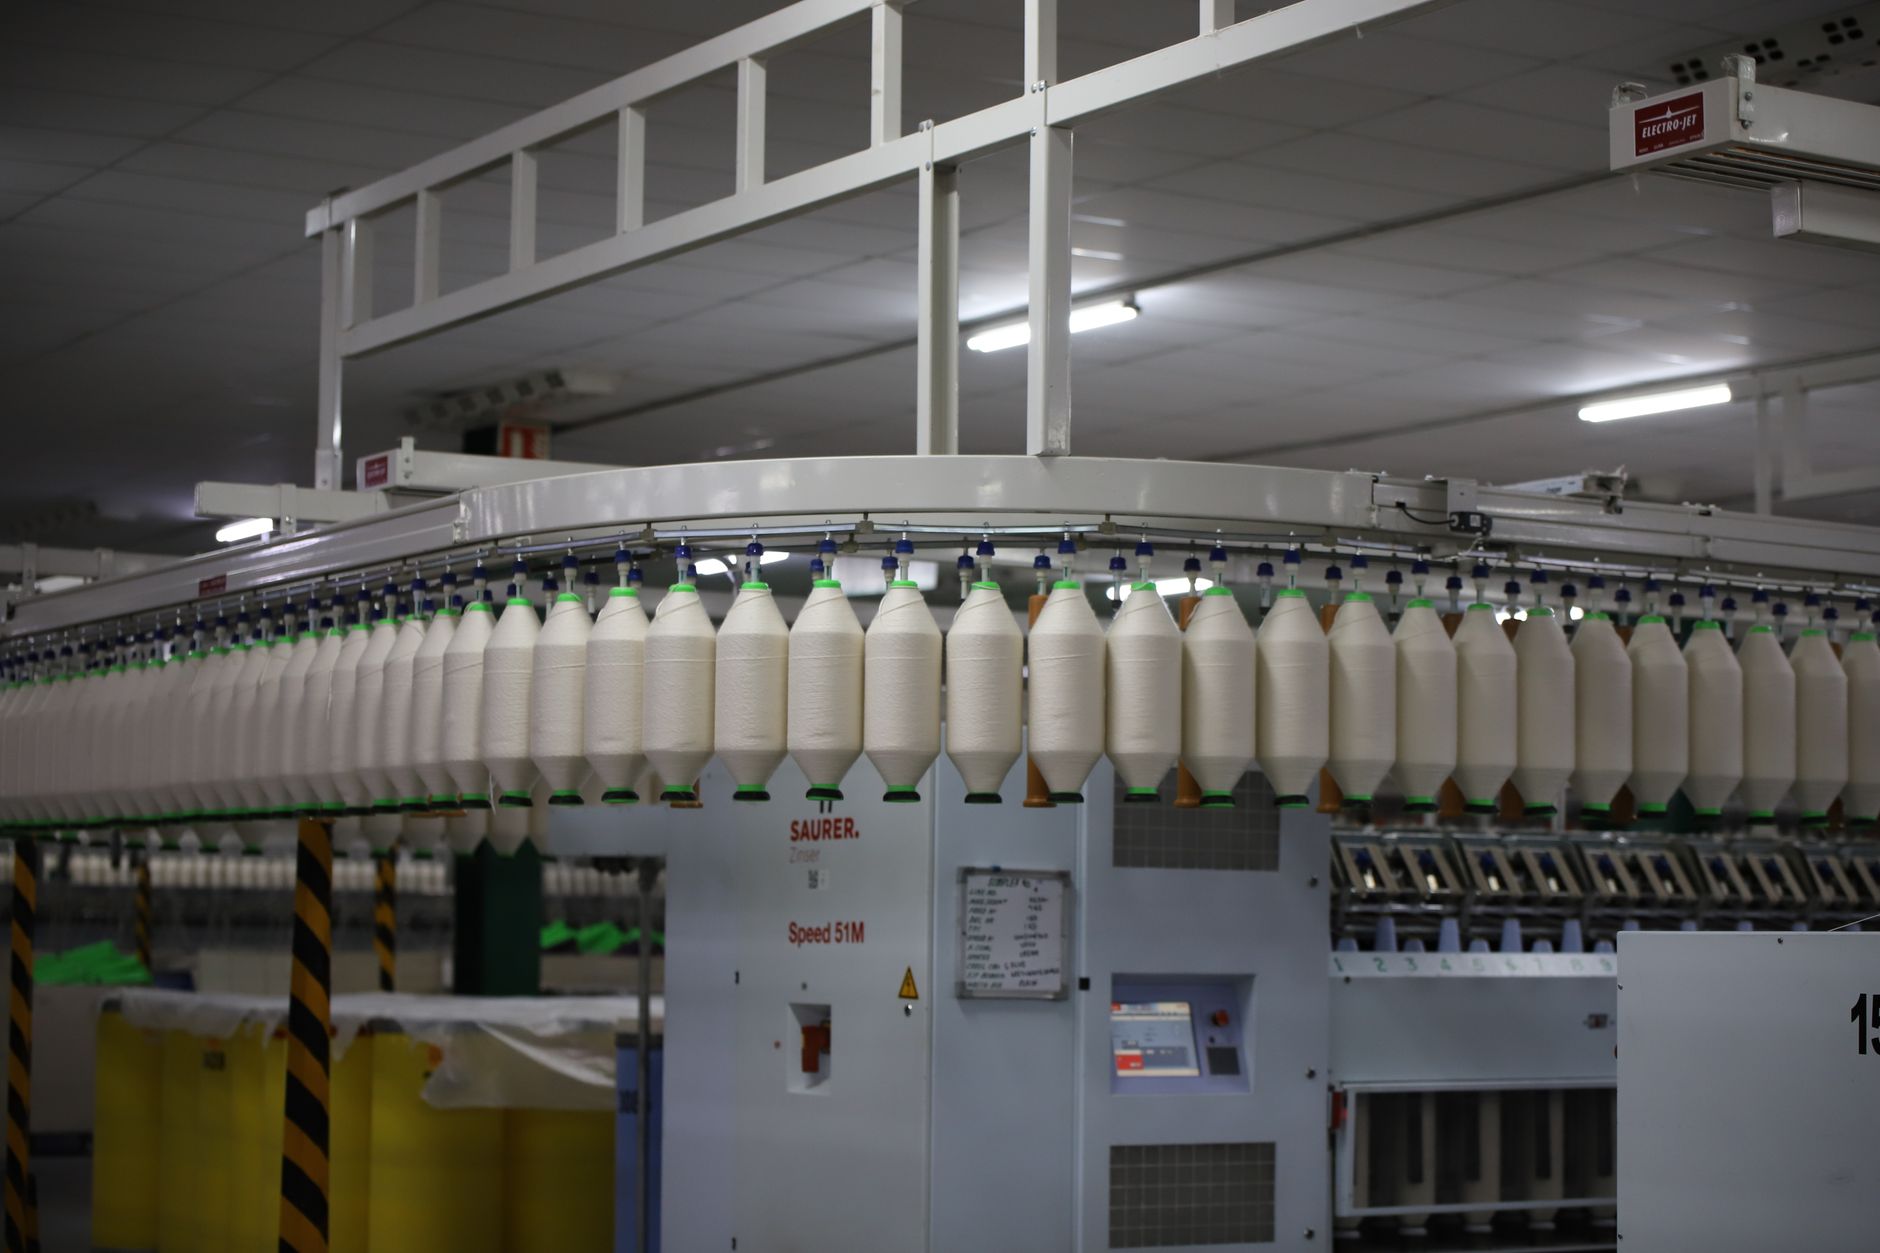
China makes roughly 37% of the world’s clothing. That single statistic understates the depth of the story. Behind it sits a network of factories, dye houses, yarn spinners, fabric mills, logistics firms, and digital platforms that collectively constitute the most capable apparel production system ever assembled. Understanding this system — how it was built, who runs it, and where it is going — is essential for any brand, importer, or investor operating in global fashion.
From Cottage Industry to Industrial Giant: The Historical Arc
China’s textile sector traces its modern roots to the 1950s state-owned mills in Shanghai, Wuhan, and Zhengzhou. But the transformation that created today’s export powerhouse began in the early 1980s in the Pearl River Delta, when Deng Xiaoping’s open-door reforms allowed township and village enterprises (TVEs) to produce garments for Hong Kong trading companies. By 1990, China had surpassed South Korea, Taiwan, and Hong Kong to become the world’s largest apparel exporter.
The accession to the World Trade Organization in 2001 removed the Multi-Fibre Arrangement quotas that had artificially capped Chinese textile exports to Western markets. Volume exploded. By 2005, the year quotas were fully phased out, China’s textile and apparel exports exceeded $115 billion. By 2023, that figure had grown to approximately $298 billion, representing more than a third of the WTO’s total recorded clothing trade.
The production clusters that emerged during this period remain the backbone of the industry today. Guangzhou and the broader Pearl River Delta dominate fast fashion, knitwear, and woven garments, with Dongguan, Foshan, and Zhongshan each hosting specialized sub-clusters. Zhejiang Province — particularly Shaoxing, which processes more than 30% of China’s polyester fabric — leads in synthetic textiles and dyeing. Jiangsu’s Suqian and Nantong districts specialize in high-end woven fabrics and home textiles. Xinjiang, despite being the subject of intense international scrutiny, produces roughly 85% of China’s raw cotton, a fact that has reshaped global sourcing decisions and compliance frameworks.
The Industry’s Structure: Who Actually Makes the Clothes
China’s textile and apparel industry is notably fragmented at the manufacturing level. The Ministry of Industry and Information Technology estimates there are over 50,000 registered garment manufacturers in China, with the vast majority being small to mid-sized operations employing 50 to 500 workers. This fragmentation is a feature, not a bug: it enables the extreme flexibility and rapid response times that global fast fashion brands depend on.
At the top of the value chain sit a handful of large integrated manufacturers. Shenzhou International Group Holdings, listed in Hong Kong, manufactures for Nike, Adidas, Uniqlo, and Puma, reporting revenues of approximately HK$26 billion (around $3.3 billion) in 2023. Hua Mao Nano-Tech and Crystal International Group are other large-scale players supplying Tier 1 global brands under long-term contracts. These companies operate at Western compliance standards, publish ESG reports, and maintain factory auditing systems that satisfy even the most demanding buyers.
Below them sits the vast middle tier — the thousands of contract manufacturers that supply mid-market brands, private label retailers, and the intermediaries who stock platforms like Amazon, ASOS, and Zalando. These factories typically operate on thin margins, compete primarily on price and speed, and are most exposed to trade policy changes including tariff shifts and quota regimes.
Shein and the Ultra-Fast Fashion Revolution
No discussion of China’s textile industry is complete without confronting Shein, the Guangzhou-headquartered ultra-fast fashion platform that rewrote the economics of global apparel retail. Founded in 2008 by Chris Xu (Xu Yangtian), Shein was initially an unremarkable drop-shipping business. The company’s transformation began around 2015 when it shifted to a model of owning its own small-batch manufacturing relationships directly in Guangzhou’s Panyu and Haizhu districts.
Shein’s innovation was essentially a data-driven version of the Pearl River Delta’s existing strengths. Rather than ordering thousands of units of a design and hoping it sold, Shein’s algorithm tests micro-batches of 100 to 200 pieces, monitors real-time click and purchase data, and scales winning designs within days. The company adds 2,000 to 10,000 new SKUs per day — a volume that makes Zara’s famous “fast fashion” cycle look glacial by comparison.
The business consequences have been dramatic. As of 2024, Shein commands an estimated 18% share of the US fast fashion market, ahead of H&M and not far behind Zara’s parent Inditex in certain categories. The company’s reported valuation has ranged between $45 billion and $66 billion depending on the funding round, though a planned IPO has faced delays due to regulatory scrutiny in multiple jurisdictions. Shein’s Guangzhou supply chain model is examined in detail elsewhere on this site — what matters here is the broader effect: Shein demonstrated to the global retail industry that a China-based company could control the entire value chain from fabric procurement to consumer doorstep and compete on price, speed, and variety simultaneously.
Temu, the De Minimis Advantage, and What Changed in 2025
Shein’s rise was partly enabled by the US de minimis rule under Section 321 of the Customs Act, which allowed packages valued under $800 to enter the United States duty-free. This gave direct-from-China platforms a structural cost advantage over brands that import inventory in bulk and pay standard duties. At its peak, Chinese e-commerce platforms were responsible for an estimated 1.3 billion de minimis shipments annually into the United States — roughly half of all such packages.
The landscape shifted materially in 2025. The US government closed the de minimis loophole for goods subject to Section 301 tariffs, which covers the vast majority of Chinese-manufactured textiles and apparel. This change altered the cost structure for platforms like Shein and Temu, which had built their US logistics models around direct small-package shipments. Both companies have responded by building or leasing US warehouse capacity and rerouting some supply through third countries, but the episode illustrates how dependent China’s fast fashion export model had become on a single regulatory provision.
For importers and brands sourcing from China, the lesson is structural: US-China trade policy directly affects the competitiveness of Chinese textile suppliers in ways that have nothing to do with manufacturing quality or efficiency. Staying current with US Trade Representative tariff schedules and Section 301 actions is not optional for anyone with significant China sourcing exposure.
China’s Textile Industry Moving Up the Value Chain
The narrative of China as purely a low-cost producer is increasingly outdated. Significant capital has flowed into technical textiles, performance fabrics, and vertically integrated manufacturing over the past decade. Several developments illustrate the shift:
Functional and performance fabrics: Companies like Toray (Japan) and Teijin have long operated in China, but domestic firms including Hyosung China, Far Eastern New Century, and Anta’s in-house materials division are developing proprietary fiber technologies. China is now the world’s largest producer of carbon fiber, a critical input for aerospace, automotive, and industrial applications.
Home textiles: Nantong-based companies including Loftex China and Sunvim Group have become top-five global suppliers of hotel towels, institutional linens, and retail home textiles. Sunvim supplies Walmart, Target, and Costco. This segment is lower-profile than apparel but generates substantial and relatively stable revenue.
Smart textiles and e-textiles: Several Shenzhen-based startups and university research groups have begun commercializing conductive fabrics, embedded sensor textiles, and temperature-regulating materials, often in partnership with defense and sports performance buyers. This remains early-stage but signals where premium production is heading.
Compliance, Xinjiang Cotton, and the Due Diligence Imperative
No Western business can operate in China’s textile sector without a clear position on Xinjiang cotton. The US Uyghur Forced Labor Prevention Act (UFLPA), signed into law in December 2021 and fully enforced from June 2022, creates a rebuttable presumption that any goods produced wholly or in part in Xinjiang are made with forced labor and are therefore barred from US import. The practical effect is a requirement for supply chain traceability that goes well beyond traditional audit frameworks.
The US Customs and Border Protection UFLPA enforcement guidance requires importers to document their entire cotton supply chain, from ginning facility through yarn spinning, weaving, dyeing, and cutting. This is technically challenging in China’s textile supply chain, where cotton from multiple origins is routinely blended at the yarn stage. Several large brands — including H&M, Nike, and Burberry — have publicly committed to sourcing no Xinjiang cotton, while others have invested in traceability technologies such as isotopic testing and blockchain-based fiber tracking.
For Chinese manufacturers supplying Western brands, the compliance burden is equally significant. Factories seeking to maintain relationships with major US and European retailers now routinely conduct third-party supply chain audits, maintain fiber certification programs, and participate in traceability pilots. This is not a temporary compliance exercise — it is a permanent structural feature of doing business in the China-to-West apparel supply chain.
Chinese Manufacturers Building Their Own Brands
The most significant long-term trend in China’s textile industry may be the shift from OEM (original equipment manufacturer) to OBM (own brand manufacturer). China’s broader OEM-to-OBM transition is well documented across sectors, and apparel is no exception. Anta Sports, which generated RMB 62.4 billion ($8.6 billion) in revenue in 2023, began as a factory in Fujian making shoes for other brands before building a portfolio that now includes Amer Sports (Arc’teryx, Salomon, Wilson). Li Ning, founded by the Olympic gymnast of the same name, has become a genuinely aspirational brand in China and is expanding in Southeast Asia and select Western markets.
At the mass market level, Chinese brands like Meters/bonwe and Semir have built domestically scaled apparel businesses that compete effectively against Zara and H&M inside China. Meanwhile, a new generation of direct-to-consumer brands — many of them founded by former Alibaba, JD, or Pinduoduo employees — are using TikTok, Xiaohongshu, and international social commerce to build brand equity without traditional retail infrastructure.
What This Means for Western Buyers and Partners
For any Western company engaged in apparel, home textiles, or technical fabric sourcing, China’s textile industry presents a paradox: it is simultaneously more capable and more complex to work with than at any previous point. Costs have risen — China’s average manufacturing wage has approximately tripled since 2010 — and compliance requirements have multiplied. Vietnam, Bangladesh, Cambodia, and Mexico have all gained apparel market share at China’s expense in price-sensitive categories.
Yet China retains structural advantages that are difficult to replicate elsewhere: the completeness of its supply chain (buttons, zippers, labels, packaging, and finishing all available within a single industrial cluster), its dyeing and finishing capacity (which remains globally unmatched in scale and variety), and its ability to handle complex, short-run orders at speeds that competing production bases cannot match. For quality-differentiated, trend-sensitive, or technically demanding apparel, China remains the default choice for most global buyers.
The bilateral trade relationship in textiles is not simply about Chinese manufacturers supplying Western brands. US-made cotton, specialty chemicals, and textile machinery all flow the other direction. American cotton growers — centered in Texas, Georgia, and Mississippi — exported over $3 billion in raw cotton to China in 2023, making China the largest export market for US cotton. This interdependence is frequently overlooked in trade policy debates but represents real economic stakes on both sides.
The Outlook: Automation, Nearshoring, and China’s Response
Automation is restructuring Chinese apparel manufacturing faster than most outside observers recognize. Sewbot technology — automated sewing machines capable of producing T-shirts and simple garments without human labor — is being deployed by firms including SoftWear Automation, Tianyuan Garment (which partnered with SoftWear), and a growing number of Zhejiang-based equipment manufacturers. While fully automated garment production remains economically marginal for complex styles, the technology is mature enough for commodity products and will reshape cost structures over the next decade.
The nearshoring trend — driven by US tariff policy and supply chain resilience concerns — has redistributed some Chinese production to Mexico, Vietnam, and Bangladesh. But Chinese manufacturers have responded by investing directly in those countries, replicating the cluster model they perfected in Guangdong and Zhejiang in new geographies. The factory may move; the management, capital, and operational know-how often remain Chinese.
Understanding China’s textile and fast fashion industry is not just about understanding where your clothes come from. It is about understanding the industrial logic — the cluster economics, the data-driven production systems, the compliance infrastructure, and the brand-building ambitions — that will define global apparel trade for the next generation.