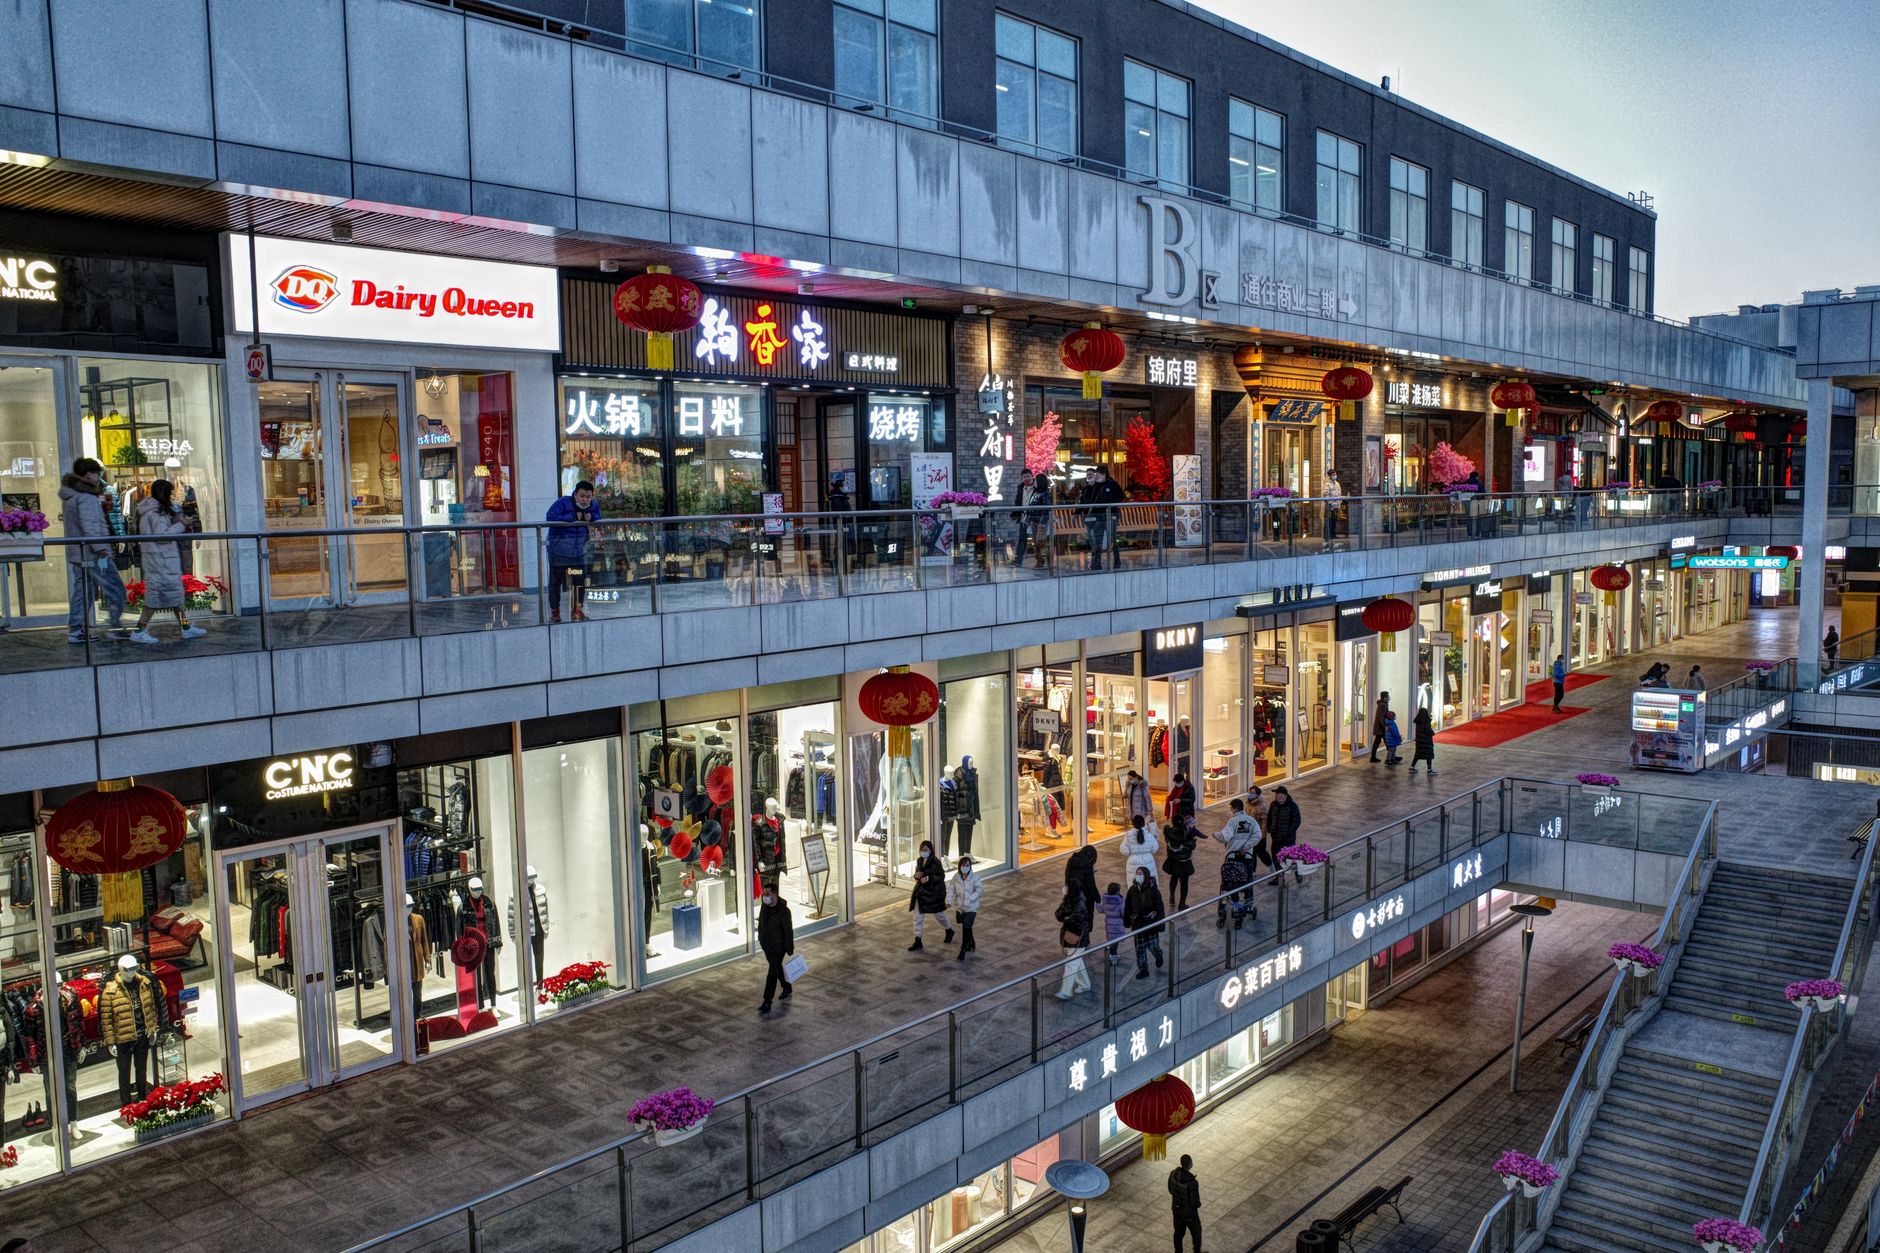
For most of the 1990s and 2000s, Western consumer brands dominated China’s aspirational middle class. Procter & Gamble, Nestlé, L’Oréal, Coca-Cola, and Unilever commanded shelf space, premium pricing, and consumer trust that Chinese domestic competitors could not match. That era is over. A generation of Chinese FMCG companies has not only reclaimed the domestic market but is beginning to challenge Western rivals globally. Understanding how this happened is no longer optional for any foreign business with a stake in China.
The Scale of the Shift
China’s retail market reached approximately RMB 47 trillion ($6.5 trillion USD) in 2025, making it the world’s second-largest consumer economy. Within it, domestic brands now hold majority share across bottled water, carbonated beverages, skincare, instant noodles, condiments, sportswear, and smartphones. According to McKinsey’s China Consumer Report, domestic brands gained 10 percentage points of market share across surveyed categories between 2019 and 2024.
This is not a story of protectionism or anti-foreign sentiment. It is a story of dramatically improved quality, digital-native marketing, hyper-localized product development, and a generation of Chinese consumers who no longer assume that “foreign” means “better.” For Western consumer brands, the implications are structural. For Chinese brands looking outward, the lessons are exportable.
Nongfu Spring: Turning Water Into a Premium Brand
Nongfu Spring was founded in 1996 by Zhong Shanshan, now one of Asia’s wealthiest individuals with a net worth exceeding $60 billion. The company began with a single insight: Chinese consumers would pay more for natural spring water if given a compelling reason. Zhong built that reason through two decades of consistent brand investment and packaging design that remained distinctly Chinese while meeting international premium standards.
The results were extraordinary. Nongfu Spring’s 2020 Hong Kong IPO raised approximately HK$33.9 billion ($4.4 billion USD). By 2024, annual revenues surpassed RMB 42 billion ($5.8 billion USD), with gross margins above 57%. Every product line — from its flagship spring water to its NFC juice range and Oriental Leaves tea beverage — reinforces a single brand value: natural sourcing and minimal processing. The company operates 12 dedicated water-source bases across China, each with public visitor centers functioning as brand-experience destinations.
The major international water brands — Evian, Volvic, Perrier — ceded ground not because of price (Nongfu Spring commands similar premiums) but because of distribution depth. Nongfu Spring built a 4-million-outlet distribution network reaching China’s third- and fourth-tier cities. European imports could not economically replicate that footprint. The lesson for foreign FMCG brands entering China: premium positioning alone does not win. Last-mile distribution capability is equally decisive.
Yuanqi Forest: The D2C Playbook That Rewrote Beverages
If Nongfu Spring represents the long game, Yuanqi Forest (元气森林) represents speed-driven disruption. Founded in 2016 by Tang Binsen, a former gaming executive, Yuanqi Forest applied mobile gaming acquisition logic to beverages: obsessively A/B testing product concepts, iterating SKUs at startup speed, and using e-commerce data to identify demand before committing to mass production.
Its flagship sparkling water — zero sugar, zero fat, zero calories, with Japanese-aesthetic packaging — became China’s fastest-growing beverage brand. By 2021, Yuanqi Forest had reached approximately RMB 7.5 billion ($1 billion USD) in revenue in five years, with a reported Series D valuation exceeding $6 billion. Coca-Cola, Nongfu Spring, and Nayuki all launched competing products within 18 months. That response is the highest form of competitive validation.
Yuanqi Forest built its distribution almost entirely through Tmall, JD.com, and social commerce before investing in offline retail — digital first, physical second. This is now the standard Chinese consumer brand launch sequence. It reduces inventory risk, generates data before committing to shelf space, and allows pricing flexibility traditional retail cannot offer. The broader FMCG revolution that these brands catalyzed is reshaping how every category competes in China.
The Guochao Movement: Nationalism as Brand Accelerant
“Guochao” (国潮), or “national trend,” is a cultural movement among Chinese millennials and Gen Z that celebrates domestic aesthetics, heritage brands, and Chinese cultural identity in consumer choices. Its business impact has been measurable. Li Ning, the sportswear brand founded by Olympic gymnast Li Ning in 1990, struggled against Nike and Adidas throughout the 2000s. When Li Ning appeared at New York Fashion Week in 2018 with a collection blending Chinese calligraphy and athletic design, the response in China was electric. The stock price tripled over two years, and annual revenues grew from RMB 10.5 billion in 2018 to RMB 22.6 billion by 2023.
Similarly, Anta Sports acquired Fila’s China business in 2009 for approximately $1 billion, then used Guochao tailwinds to push its own Anta brand to revenues exceeding RMB 29.7 billion ($4.1 billion USD) by 2023 — larger than Nike’s or Adidas’ Chinese revenues.
For Western brands, Guochao is not simply a marketing headwind. It is a structural shift in cultural authority. Strategies that position Western products as aspirational status symbols face declining returns. Value propositions must rest on specific functional or experiential differentiation — not heritage alone.
Beauty: The Digital Battlefield
In 2015, the top-10 skincare brands in China by retail sales were almost entirely Western or Japanese: L’Oréal Paris, Lancôme, Estée Lauder, Shiseido, SK-II, and Olay. By 2023, domestic brands including Proya, Florasis, and Winona had captured top-10 positions across multiple subcategories, driven by ingredient innovation, livestream commerce competency, and faster product-development cycles.
Proya’s 2023 revenue of RMB 8.97 billion represented 37% year-on-year growth. The company launches over 100 new SKUs annually and uses Douyin livestream data to move formulations from concept to mass production in 60 to 90 days. That speed is structurally impossible for multinationals whose product-development cycles run 18 to 36 months through global R&D and regulatory approval processes.
Strategic Takeaways for US and Western Businesses
The rise of China’s domestic consumer brands is a market reality to understand and, where possible, partner with. Five strategic takeaways stand out:
Quality parity is achieved. The assumption that Chinese domestic goods are lower quality than Western imports no longer holds across consumer categories. US importers and retailers should be seeking Chinese FMCG partnerships actively, not reactively.
The D2C data advantage is real. Chinese brands have access to consumer behavior data through Tmall, JD, Douyin, and WeChat at granularity and speed that Western companies operating in China cannot match without dedicated digital commerce teams. The shift from OEM to OBM manufacturing is underpinned by this data advantage.
Partnership beats replication. The most successful foreign consumer brands in China — including Yum China’s KFC and Pizza Hut model — succeeded by partnering deeply with Chinese distribution, marketing, and supply chain expertise. Brands that treated China as a market to be served from headquarters have consistently underperformed those that built locally.
Outbound Chinese brands are coming. Nongfu Spring, Yuanqi Forest, Li Ning, Anta, Proya — none are yet household names in the United States. That will change. The trajectory of Luckin Coffee — which reached 18,000 outlets in seven years — demonstrates the pace at which Chinese consumer brands can scale. US retailers and distributors who establish relationships now will be better positioned than those who engage reactively.
Regulatory Context for US-China Consumer Trade
US companies importing Chinese consumer goods must navigate CPSC product safety requirements and FDA regulations for food, beverages, cosmetics, and dietary supplements. Labeling and testing standards differ materially from Chinese domestic requirements. On the Chinese side, the Ministry of Commerce of the People’s Republic of China (MOFCOM) publishes export procedure guidance, while the US International Trade Administration’s Consumer Goods market intelligence portal provides regularly updated analysis of import trends, tariff schedules, and market access conditions for US businesses.
The brands profiled here are not outliers. They are the leading edge of a competitive cohort that Western businesses have limited time to understand before it arrives on their doorstep — and that represents genuine partnership opportunity for those willing to engage early.