Walk into any smartphone factory, wind turbine assembly line, or electric vehicle plant on earth, and you will find the same invisible dependency: rare earth elements sourced predominantly from China. The 17 metallic elements that make up the rare earth group — from cerium and lanthanum to neodymium and dysprosium — are not household names, but they are the foundational inputs behind everything from permanent magnets and fiber optic cables to military radar systems and MRI machines.
China does not just mine rare earths. It refines them, processes them, and manufactures the downstream components that the world’s highest-value industries cannot function without. Understanding how this dominance was built — and what it means for companies operating across US-China trade corridors — is essential for any serious business professional in 2026.
The Numbers Behind the Dominance
China accounts for approximately 60 to 70 percent of global rare earth mine production and over 85 percent of global rare earth processing and separation capacity, according to data published by the U.S. Geological Survey (USGS). In the processing stage, where mined ore is chemically separated into usable compounds, China’s share approaches near-monopoly levels for many individual elements.
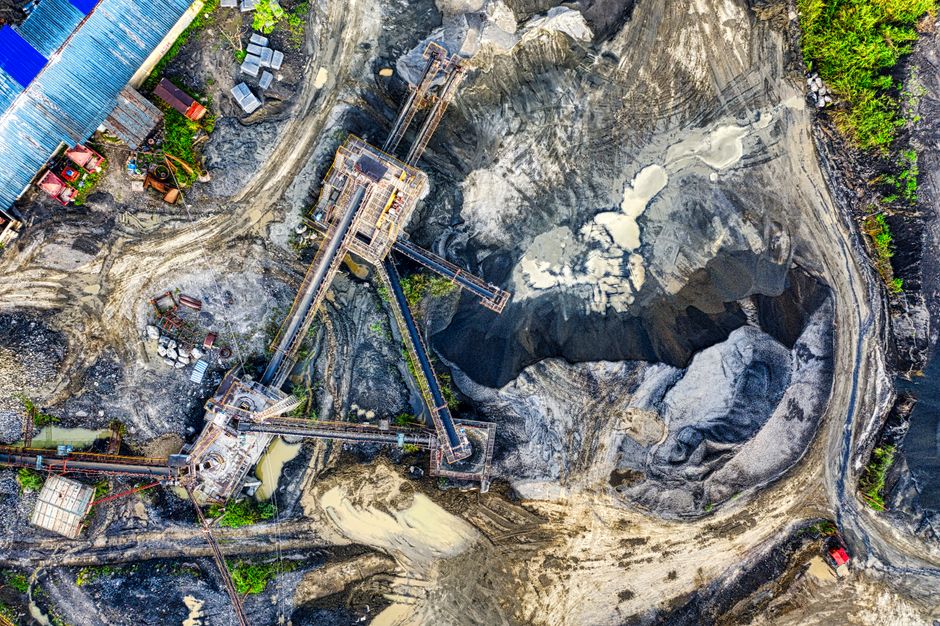
The six state-designated rare earth mining bases — concentrated in Inner Mongolia, Jiangxi, Fujian, Guangdong, Sichuan, and Yunnan — underpin this position. China Northern Rare Earth Group (北方稀土), headquartered in Baotou, Inner Mongolia, is the world’s largest rare earth producer by volume. Its Bayan Obo deposit is the single richest rare earth deposit on the planet, estimated to hold roughly 35 percent of known global reserves. The company’s parent, China Baotou Steel Rare-Earth Group, processes and refines material not only from Bayan Obo but from contracted deposits across the country.
In southern China, China Southern Rare Earth Group dominates the extraction of ion-adsorption clays in Jiangxi and Guangdong — the source of the heavy rare earth elements (dysprosium, terbium, holmium) that are particularly critical for high-performance permanent magnets. Southern rare earths are harder to process than their northern counterparts and require hydrometallurgical techniques in which Chinese companies have accumulated decades of proprietary expertise.
How China Built This Position
China’s rare earth dominance was not accidental. It was the product of deliberate industrial policy, significant state investment, and strategic tolerance of environmental costs that Western mining jurisdictions could not replicate.
The story begins in the 1980s when Deng Xiaoping, on a visit to Inner Mongolia, reportedly said: “The Middle East has oil; China has rare earths.” Through the 1990s and 2000s, China rapidly scaled extraction capacity while maintaining export prices low enough to undercut non-Chinese producers. Mountain Pass, the largest rare earth deposit in the United States, was operated by Molycorp until depressed global prices made it economically unviable. It entered bankruptcy in 2015. MP Materials, which now owns the site, has rebuilt operations to roughly 15,000 metric tons of rare earth content annually as of 2025 — but still ships significant ore to China for separation.
Simultaneously, Chinese firms invested heavily in processing infrastructure. Separation and refining facilities in Jiangxi’s Ganzhou city — often called “China’s rare earth capital” — became the world’s most capable cluster for heavy rare earth processing. This created a structural moat: even countries with substantial rare earth deposits found it cheaper and faster to ship ore to China for processing than to build competing refinery capacity domestically.
Beijing reinforced this advantage through quota systems, export licenses, and, more recently, direct export controls. In 2023 and 2024, China imposed licensing requirements on gallium, germanium, and graphite — all materials with significant rare earth adjacency and semiconductor applications. These moves signaled that rare earth and critical mineral trade policy had become a formal instrument of geopolitical leverage, not merely a commercial question. For a deeper look at how those controls are being wielded tactically, see our analysis of China’s Rare Earth Strategy and how Beijing controls the minerals the world economy cannot live without.
Why Rare Earths Are Genuinely Irreplaceable
The term “rare earth” is slightly misleading: most rare earth elements are not geologically rare. Cerium, for example, is more abundant in the earth’s crust than copper. What makes them rare — and strategically critical — is the difficulty of finding them in economically mineable concentrations and the complexity of separating individual elements from ore that contains a mixture of 17 closely related metals.
Their applications are concentrated in precisely the sectors that define the current technology transition:
Permanent magnets: Neodymium-iron-boron (NdFeB) magnets are the most powerful permanent magnets known. A single EV motor uses roughly 1 to 2 kilograms of NdFeB magnet material. Wind turbine generators can require 600 kilograms per megawatt of capacity in direct-drive designs. Global EV production in 2025 exceeded 20 million units, with wind turbine installations accelerating to meet net-zero targets. Every unit requires rare earth magnets — and China controls the magnet production supply chain from mining through finished component.
Phosphors and LEDs: Europium and terbium underpin the red and green phosphors in LED lighting and display panels. The transition from fluorescent to LED lighting over the past decade represented one of the largest rare earth demand shifts in history.
Defense and aerospace: Samarium-cobalt magnets power precision-guided munitions, fighter jet actuators, and submarine sonar systems. The U.S. Department of Defense has formally identified rare earth supply chain vulnerability as a national security concern, as documented in the U.S. Department of Energy’s Critical Materials Assessment.
Catalysts and glass: Lanthanum and cerium are used in petroleum fluid catalytic cracking, critical for refining high-octane gasoline. Cerium oxide is the primary glass polishing compound for semiconductor wafers, optical lenses, and flat panel displays.
The Downstream Value Chain: Where the Real Power Sits
Mining is only the first layer of China’s rare earth advantage. The strategic depth lies in the downstream value chain — from separated rare earth oxides, to rare earth metals and alloys, to functional components like permanent magnets and phosphors.
Zhongke Sanhuan (中科三环), JL MAG Rare-Earth (金力永磁), and Earth-Panda (英洛华) are among China’s dominant NdFeB magnet manufacturers. These companies supply directly to global automakers, wind turbine OEMs, and consumer electronics assemblers. Zhongke Sanhuan reported revenue of approximately RMB 5.3 billion (~$730 million) in 2024, largely driven by EV and wind energy demand.
For global manufacturers, the dependency runs through every processing stage to finished functional components. A European automaker sourcing EV magnets, a U.S. defense contractor specifying samarium-cobalt actuators — all depend on Chinese industrial capacity that cannot be replicated on a five-year timeline.
This vertical depth is directly relevant to companies tracking the battery supply chain. Our coverage of Ganfeng Lithium and Tianqi Lithium documents how a similar model of mining-to-processing dominance has been applied to the lithium supply chain — and the strategic implications are structurally comparable.
What This Means for US-China Trade Professionals
For business professionals operating at the US-China interface, rare earth dependency creates both risk and opportunity, depending on where in the value chain you sit.
For importers of manufactured goods: Components in your supply chain almost certainly contain Chinese-sourced rare earth materials or Chinese-manufactured rare earth components. Supplier due diligence should map rare earth inputs at least two tiers deep. This is particularly urgent for companies selling into U.S. defense or government procurement channels, where NDAA restrictions on Chinese-sourced minerals are expanding. This connects to the broader industrial policy picture covered in our analysis of Made in China 2025 and its implications for US businesses.
For companies exporting to China: Western rare earth producers — whether Australian, Canadian, or American — find China a difficult market to penetrate at the processing and magnet level precisely because domestic capacity is subsidized and protected. Export of raw ore or concentrates to Chinese processors remains the most commercially viable near-term path, though this reinforces the dependency chain rather than breaking it.
For investors and M&A professionals: The rare earth sector outside China is among the most actively government-subsidized in the current industrial policy environment. Companies with permitted, funded, and technically viable rare earth projects in Five Eyes-aligned countries are attracting strategic capital at valuations that would have seemed implausible a decade ago.
For business professionals navigating this environment, the essential discipline is specificity: know which rare earth elements your supply chain depends on, at what processing stage, and from which Chinese entity. General awareness of “China’s rare earth dominance” is no longer sufficient. The commercial and regulatory landscape rewards those who can map their exposure with precision.
”