In the span of a single decade, China produced some of the world’s most valuable education technology companies — and then watched as its own government dismantled them in a single regulatory sweep. The story of China’s EdTech sector is one of the most instructive in modern business: a tale of explosive growth, global ambition, near-total domestic collapse, and cautious reinvention that carries real implications for anyone operating at the intersection of education, technology, and cross-border commerce.
The Boom: Building a $120 Billion Market
China’s appetite for education has always been exceptional. Rooted in the Confucian tradition of scholarship and amplified by fierce competition for university places through the gaokao, Chinese families historically allocated a disproportionate share of household income to supplementary tutoring. By 2020, the private tutoring market was estimated at roughly $120 billion annually.
TAL Education Group, founded in 2003 by Zhang Bangxin, industrialized this demand at scale. By the late 2010s, TAL enrolled over 5 million students in math and science programs, operated centers in 70+ cities, and listed on the New York Stock Exchange at a market capitalization briefly exceeding $30 billion.
New Oriental Education (NYSE: EDU), founded in 1993 by Yu Minhong, built a broader empire: university entrance coaching, English language programs, study-abroad consulting, and children’s enrichment. At its peak, New Oriental operated 1,500+ learning centers, employed over 100,000 teachers, and generated annual revenues exceeding $4 billion. Yu’s story — failing the gaokao twice before building a multi-billion dollar company teaching English — became one of China’s defining entrepreneurial narratives.
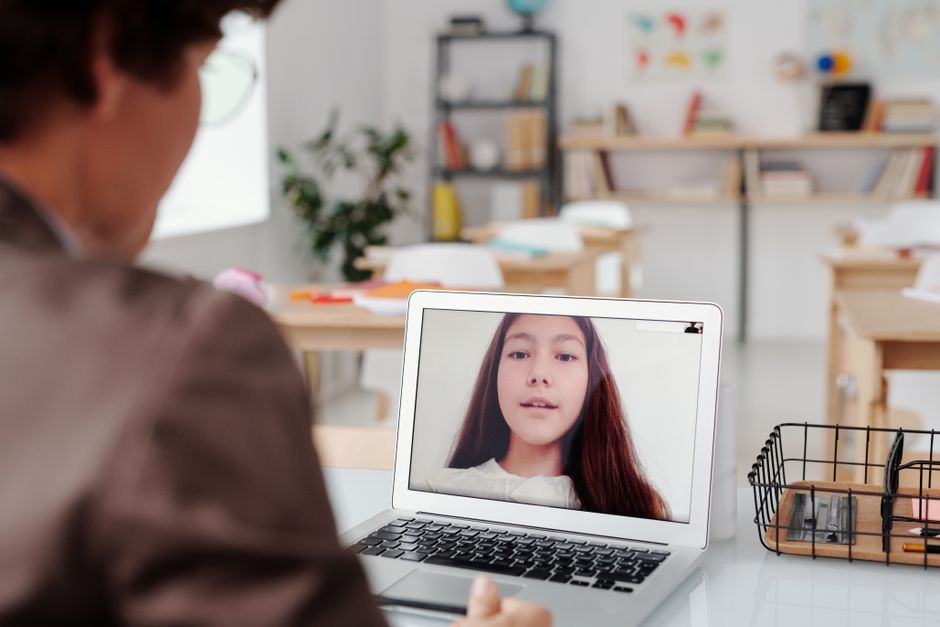
VIPKID, founded in 2013 by Mi Wenjuan and backed by Tencent, Sequoia Capital China, and Kobe Bryant’s Bryant Stibel fund, pioneered a genuinely bilateral model: Chinese children aged 4 to 15 taking one-on-one English lessons via video with North American teachers earning $14-$22 per hour. At peak in 2019, VIPKID had 700,000 enrolled students, 100,000 foreign teachers, and a valuation of approximately $4.5 billion.
The Regulatory Earthquake: July 2021
On July 24, 2021, China’s State Council issued the “Double Reduction” policy (双减), prohibiting for-profit tutoring in core academic subjects for K-9 students on weekends, holidays, and vacations. It also barred new foreign investment in the sector and blocked existing operators from capital markets activity.
The policy framed the tutoring industry as exacerbating inequality, burdening families, and suppressing the birth rate. The financial fallout was immediate: TAL’s market capitalization fell from $35 billion to under $2 billion within months. New Oriental lost over 90 percent of its NYSE value. VIPKID terminated most of its foreign teacher contracts. The Nasdaq Golden Dragon China Index dropped 40 percent in the months following the announcement.
How the Giants Pivoted
What happened next was a case study in corporate reinvention.
New Oriental launched Dongfang Zhenxuan (Oriental Selection), a Douyin live-streaming commerce channel that blended product sales with bilingual cultural education. A clip of English teacher Dong Yuhui selling shrimp while quoting literature went viral in mid-2022, generating millions of followers overnight. New Oriental’s Hong Kong shares surged over 400 percent within days. Dongfang Zhenxuan became a $1 billion+ revenue business, demonstrating that a company can transform its identity while retaining its core competency: engaging, high-quality teaching.
TAL Education shifted aggressively into non-restricted segments: adult vocational training, AI-powered adaptive learning tools, and STEM enrichment for high school students. TAL’s investment in education AI infrastructure repositioned it as a technology vendor to schools rather than a direct competitor to public education.
VIPKID restructured toward adult language learning and corporate English training — segments explicitly exempt from the 2021 rules. Its North American teacher network was largely wound down, representing the most direct bilateral casualty of the policy shift. As covered in our analysis of ByteDance’s global expansion strategy, Chinese tech companies facing domestic regulatory pressure increasingly pivot to international markets — and EdTech is no exception.
What Foreign Businesses Should Know Now
Adult and Vocational Education Is Wide Open
The Double Reduction policy applied narrowly to K-9 academic subjects. Adult professional development, vocational certification, language learning for adults, corporate training, and university test preparation remain legal and growing. The market for adult upskilling — particularly English, data science, and professional certification — is estimated at over $30 billion annually. Companies like Wall Street English and EF Education First continue to serve millions of Chinese adult learners.
AI in Education Is a Policy Priority
China’s Ministry of Education has actively promoted AI-powered adaptive learning tools in public schools. iFLYTEK’s education AI products now reach over 50 million students. Squirrel AI, which uses machine learning to personalize lesson pacing, operates in hundreds of schools. Western AI education companies with adaptive learning, speech recognition, or assessment technology have a clear entry point as technology vendors to government-approved platforms — a very different model than direct-to-consumer tutoring.
Baidu’s ERNIE Bot and NetEase’s gamified learning products represent the convergence of AI and education that regulators have been more permissive about than traditional tutoring — an emerging sector worth monitoring closely.
Content Licensing and Curriculum Export
Demand for internationally recognized curriculum content remains strong at the high school and university level. International Baccalaureate, Cambridge A-Level, and AP programs continue to operate and expand. For Western educational publishers and assessment organizations, China represents a long-term licensing opportunity — though foreign equity restrictions in K-12 schools require careful structuring, typically through cooperation agreements or minority stakes in approved entities.
New Oriental’s Bilateral Legacy
New Oriental specifically shaped US-China bilateral relations in a concrete way. For over two decades, it prepared millions of Chinese students for the SAT, GRE, GMAT, and TOEFL — examinations that served as gateways to US university enrollment. At peak, over 300,000 Chinese students enrolled annually in American universities, contributing an estimated $15 billion per year to the US higher education economy. New Oriental’s study-abroad consulting division processed hundreds of thousands of US university applications, and its English programs created a generation of Chinese professionals capable of working in multinational environments.
The reduction in Chinese international student enrollment that followed COVID-19, rising US visa denials, and broader bilateral tensions represents a material loss to both sides — and a reminder that the EdTech infrastructure New Oriental built was partly what made that exchange possible at scale. Hangzhou’s emergence as China’s tech and e-commerce capital, as explored in our Hangzhou city guide, offers a comparable story of how ecosystem concentration creates disproportionate global connectivity.
The Path Forward
The era of foreign companies building direct-to-consumer K-12 tutoring businesses in China is over. The era of technology licensing, AI partnership, adult learning, and curriculum cooperation is beginning. China’s Ministry of Education reported in 2023 that unlicensed tutoring institutions had declined by over 90 percent since 2021 — meaning the market has formalized, shifted demographics, and embedded into technology infrastructure, but has not disappeared.
For companies approaching this market with the right structure, a $60 billion+ addressable opportunity remains very much in play.
For policy and sector data, refer to the Chinese Ministry of Education (教育部) and the US Department of Commerce Country Commercial Guide: China Education Sector.