When Liu Qiangdong founded JD.com in 1998 as a counter selling magneto-optical products in Beijing’s Zhongguancun electronics district, no one predicted it would grow into China’s second-largest e-commerce platform by revenue, a company processing over 4 billion orders annually and operating one of the world’s most sophisticated logistics networks. JD.com (also known as Jingdong, ticker: JD on Nasdaq) reported net revenues of approximately RMB 1.08 trillion ($149 billion) in 2023, making it one of the largest companies in China and a defining force in global retail infrastructure.
Understanding JD.com is essential for any US or international business engaged in China commerce. The company’s model, its infrastructure, its regulatory entanglements, and its ongoing global expansion all carry direct implications for sourcing professionals, logistics executives, consumer brands, and trade policy analysts.
From Electronics Counter to National E-Commerce Platform
Liu’s original Jingdong store sold optical products and later expanded into consumer electronics. The SARS epidemic of 2003 forced the closure of his physical stores, prompting a pivot online — a decision that defined the company’s trajectory. By 2007, Liu made the move that would distinguish JD from every Chinese competitor: he began building his own logistics network.
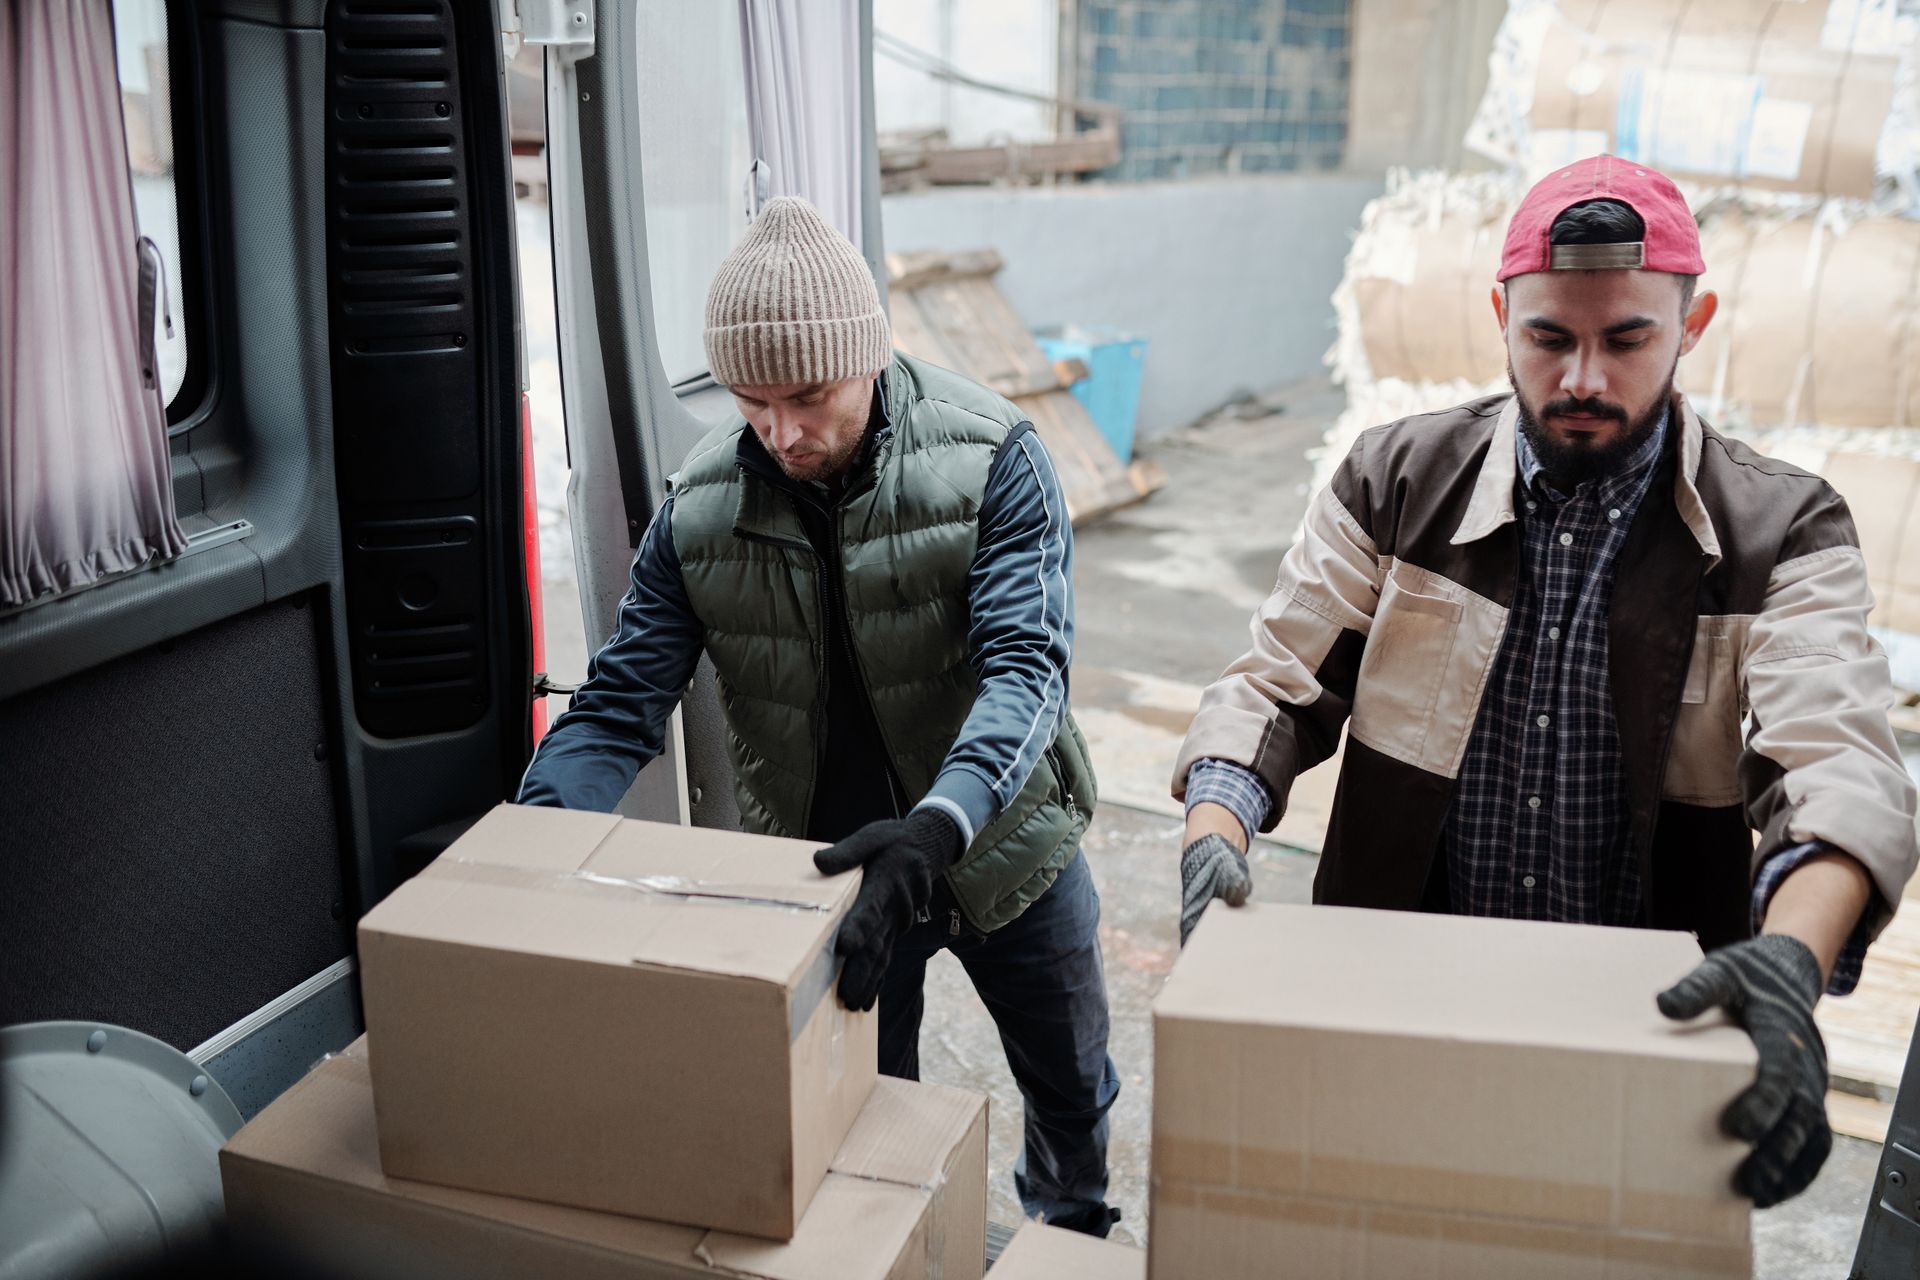
That bet was expensive and controversial. While Alibaba’s Taobao grew by acting as a pure marketplace, Liu insisted on owning the warehouse, last-mile delivery, cold chain, and customer experience. JD invested billions in automated fulfillment centers and neighborhood delivery stations across hundreds of cities, recruiting a direct permanent workforce rather than contractors. Today, JD Logistics operates over 1,600 warehouses exceeding 30 million square meters — the largest fulfillment footprint of any e-commerce company in Asia.
The JD Model: Why Logistics Is the Moat
JD’s strategic logic runs counter to the asset-light marketplace model that defined Western e-commerce orthodoxy. Where Amazon and Alibaba aggregate millions of merchants and push logistics to fragmented carriers, JD built vertically integrated retail and fulfillment infrastructure.
The results are measurable. JD offers same-day and next-day delivery in hundreds of Chinese cities — dependent on warehouse density and pre-positioned inventory. In 2023, approximately 90% of self-operated orders were fulfilled same-day or next-day. The company also operates dedicated cold-chain infrastructure serving grocery, pharmaceutical, and premium food categories.
JD’s technology investment amplifies this infrastructure. The company has deployed autonomous delivery robots, warehouse picking systems, and drone delivery in rural Sichuan and Shaanxi. JD Logistics listed separately on the Hong Kong Stock Exchange in May 2021, raising HK$24 billion ($3.1 billion) in its IPO — confirming that the logistics arm had standalone institutional value well beyond its support function for JD retail.
JD’s Position in China’s E-Commerce Hierarchy
China’s e-commerce market is larger than the US and European markets combined by transaction volume. Within that market, JD occupies a distinct strategic position. Alibaba (Taobao + Tmall) dominates general merchandise at scale; Pinduoduo disrupted from below with group-buying and rural commerce. JD commands the premium center: it holds the highest average order value in Chinese e-commerce and is the preferred platform for electronics, appliances, luxury goods, imported food, and healthcare.
This positioning matters for foreign brands. JD’s direct-sales model means brand partners engage with a professional merchandising team rather than a fragmented merchant ecosystem. Global companies including Apple, Procter and Gamble, and Nike maintain flagship stores on JD. The company has also invested in blockchain-based product traceability and authenticity verification — significant advantages for import brands concerned about counterfeiting.
JD Health, JD Industrials, and the Ecosystem Strategy
Like Alibaba and Tencent, JD has pursued a diversification strategy beyond core retail. Two subsidiaries illustrate the ambition most clearly.
JD Health, which listed on the Hong Kong Stock Exchange in December 2020 raising HK$26.2 billion, operates China’s largest online pharmacy and has built a telemedicine platform with over 150,000 licensed physicians. Its model integrates prescription drug procurement, digital health consultations, and corporate health benefits management — building a healthcare access layer on top of JD’s logistics infrastructure.
JD Industrials targets enterprise procurement. China’s manufacturers spend trillions annually on MRO supplies, industrial components, and production materials — a market historically dominated by fragmented offline distributors. JD digitizes this procurement chain and serves over 1.5 million corporate customers, with particular traction in automotive, electronics, chemicals, and heavy industry.
Regulatory Scrutiny and the Liu Qiangdong Factor
JD.com has navigated a challenging regulatory environment that has reshaped every major Chinese tech platform since 2020. The company’s exposure to China’s platform economy regulations — covering data privacy, algorithmic recommendation, market competition, and financial services — required significant compliance investment and management bandwidth. Unlike Alibaba, which faced a RMB 18.2 billion antitrust fine in 2021 for exclusivity practices, JD largely avoided the most severe regulatory penalties, in part because its direct-sales model differs structurally from a pure marketplace.
The more prominent regulatory and reputational complication involves Liu Qiangdong personally. Liu was arrested in Minneapolis in September 2018 on a sexual misconduct allegation; charges were later dropped by prosecutors, and Liu denied all allegations. He subsequently settled a civil suit filed in the US in 2022. The episode created sustained investor uncertainty and damaged JD’s reputation in international capital markets, contributing to a prolonged period of stock underperformance despite solid operating results. Liu stepped back from day-to-day management in 2022, transitioning operational responsibilities to a new management team while retaining majority voting control through a dual-class share structure.
JD’s International Strategy: Southeast Asia and Beyond
JD’s international ambitions have been more targeted than Alibaba’s. The company has focused primarily on Southeast Asia, investing in Indonesia’s Tokopedia (now GoTo Group) and establishing operations in Thailand and Indonesia. JD leverages its logistics expertise in markets where e-commerce infrastructure is still developing and where its premium positioning attracts middle-class urban consumers.
For US businesses, JD’s international expansion creates two distinct opportunity sets. First, American brands selling into Southeast Asian markets may encounter JD-affiliated logistics and retail infrastructure as a distribution partner option. Second, JD’s growing sophistication in cross-border e-commerce infrastructure — including its cross-border fulfillment systems that also position it alongside competitors like Cainiao and SF International — creates new channels for importing foreign goods into China’s bonded zone network.
What JD.com Means for US-China Business Relations
JD.com’s evolution carries several direct implications for American businesses and policymakers engaged in US-China trade.
For US brands selling into China: JD represents the single most credible platform for premium consumer goods, electronics, pharmaceuticals, and industrial products in the Chinese market. JD’s authenticated direct-sales model reduces counterfeit risk significantly compared to open marketplace channels. Companies including Costco, Walmart, and dozens of American consumer brands have established long-term distribution agreements with JD. The Alibaba ecosystem and JD.com together account for the majority of China’s B2C e-commerce revenue, and any serious China market entry strategy must engage both.
For US logistics professionals: JD Logistics’ capabilities set a technical benchmark that is increasingly referenced in conversations about global supply chain modernization. Its automation density, drone delivery progress, and cold-chain infrastructure represent genuine operational innovation that has emerged largely independently of Western logistics companies. American logistics executives visiting China frequently cite JD’s fulfillment centers as the most operationally advanced they have encountered anywhere globally.
For trade policy analysts: As a Nasdaq-listed Chinese company, JD is subject to SEC disclosure requirements and PCAOB audit oversight — the same framework that nearly caused mass delisting of Chinese firms in 2022. JD has maintained compliance and its Nasdaq listing, making it a useful reference case for US-China capital market negotiations. The US Securities and Exchange Commission maintains ongoing guidance on Chinese company disclosure requirements that affects JD and its peers.
JD and China’s Digital Commerce Infrastructure
JD.com does not operate in isolation. It sits within the broader ecosystem of Chinese digital commerce infrastructure that includes Tencent (which holds a significant minority stake in JD and integrates JD’s shopping into WeChat’s 1.3 billion-user platform), Pinduoduo, Douyin Commerce, and a growing number of vertical platforms. Understanding where JD sits competitively requires understanding this ecosystem as a whole — including the Made in China 2025 industrial policy framework that shapes government priorities around domestic digital infrastructure and advanced manufacturing sectors where JD’s industrial procurement business plays a direct enabling role.
The Chinese Ministry of Commerce (MOFCOM) has also consistently cited JD’s logistics infrastructure as a model for digital economy development in lower-tier cities and rural areas, reflecting the government’s interest in using e-commerce as a mechanism for rural income growth and internal consumption expansion.