Meituan is one of the most consequential technology companies most Western executives have never studied closely. As of 2026, it serves more than 700 million annual active users, operates in over 2,800 cities and counties across China, and processes food delivery orders at a volume that dwarfs what DoorDash, Uber Eats, and Just Eat Takeaway handle combined. Yet when European and American platforms attempt to replicate its model, they consistently fall short — not because of a single feature gap, but because of a structural moat built over fifteen years that goes far beyond the delivery bag.
From Group Buying to Platform Empire
Meituan was founded in 2010 by Wang Xing, a serial entrepreneur who had previously built Chinese equivalents of both Facebook and Twitter. He launched Meituan as a Groupon clone during the group-buying craze, but saw the model differently from his peers: not as a discount mechanism, but as a demand aggregation tool applicable to any local service.
The “Thousand Regiments War” of 2010 to 2012 saw more than 5,000 group-buying sites compete in China. By 2014, only a handful survived. Meituan’s persistence came from operational discipline, cost structure optimization, and a willingness to accept near-zero margins in pursuit of scale. Wang Xing would later describe this period as the company’s “long march” — a phrase chosen deliberately for its cultural resonance and its implication of hardship endured in service of a decisive long-term advantage.
In 2015, Meituan merged with Dianping — China’s equivalent of Yelp, with a restaurant review database built since 2003. The deal gave Meituan something no food delivery startup could acquire organically: the deepest local services database in the country, enriched with user reviews and preference data accumulated over more than a decade.
The Super-App Architecture: Why One App Beats Five
In Western markets, consumers typically use separate apps for food delivery, grocery delivery, hotel booking, movie tickets, and restaurant discovery. In China, Meituan handles all of these within a single interface — and the integration is structural, not cosmetic.
When a user books a hotel through Meituan, the platform knows their destination and can surface restaurant recommendations. When a user orders a specific cuisine three times per week, the algorithm can match that behavior to promotional coupons for nearby untried restaurants, increasing order frequency across the entire dining vertical. This cross-vertical data loop creates a compounding personalization advantage that standalone apps cannot replicate.
As of 2025, Meituan’s in-app categories include food delivery, dine-in reservations, hotel booking, flight and train tickets, ride-hailing, bike-sharing, grocery delivery, beauty appointments, movie tickets, and medical booking. The 700-million-plus user base means Meituan processes behavioral data at a scale no single-category Western competitor can approach. DoorDash cannot beat Meituan by improving its delivery algorithm — the advantage is in the breadth of life-service data that allows Meituan to intercept consumer intent across twenty-plus categories simultaneously.
The Delivery Network as Infrastructure
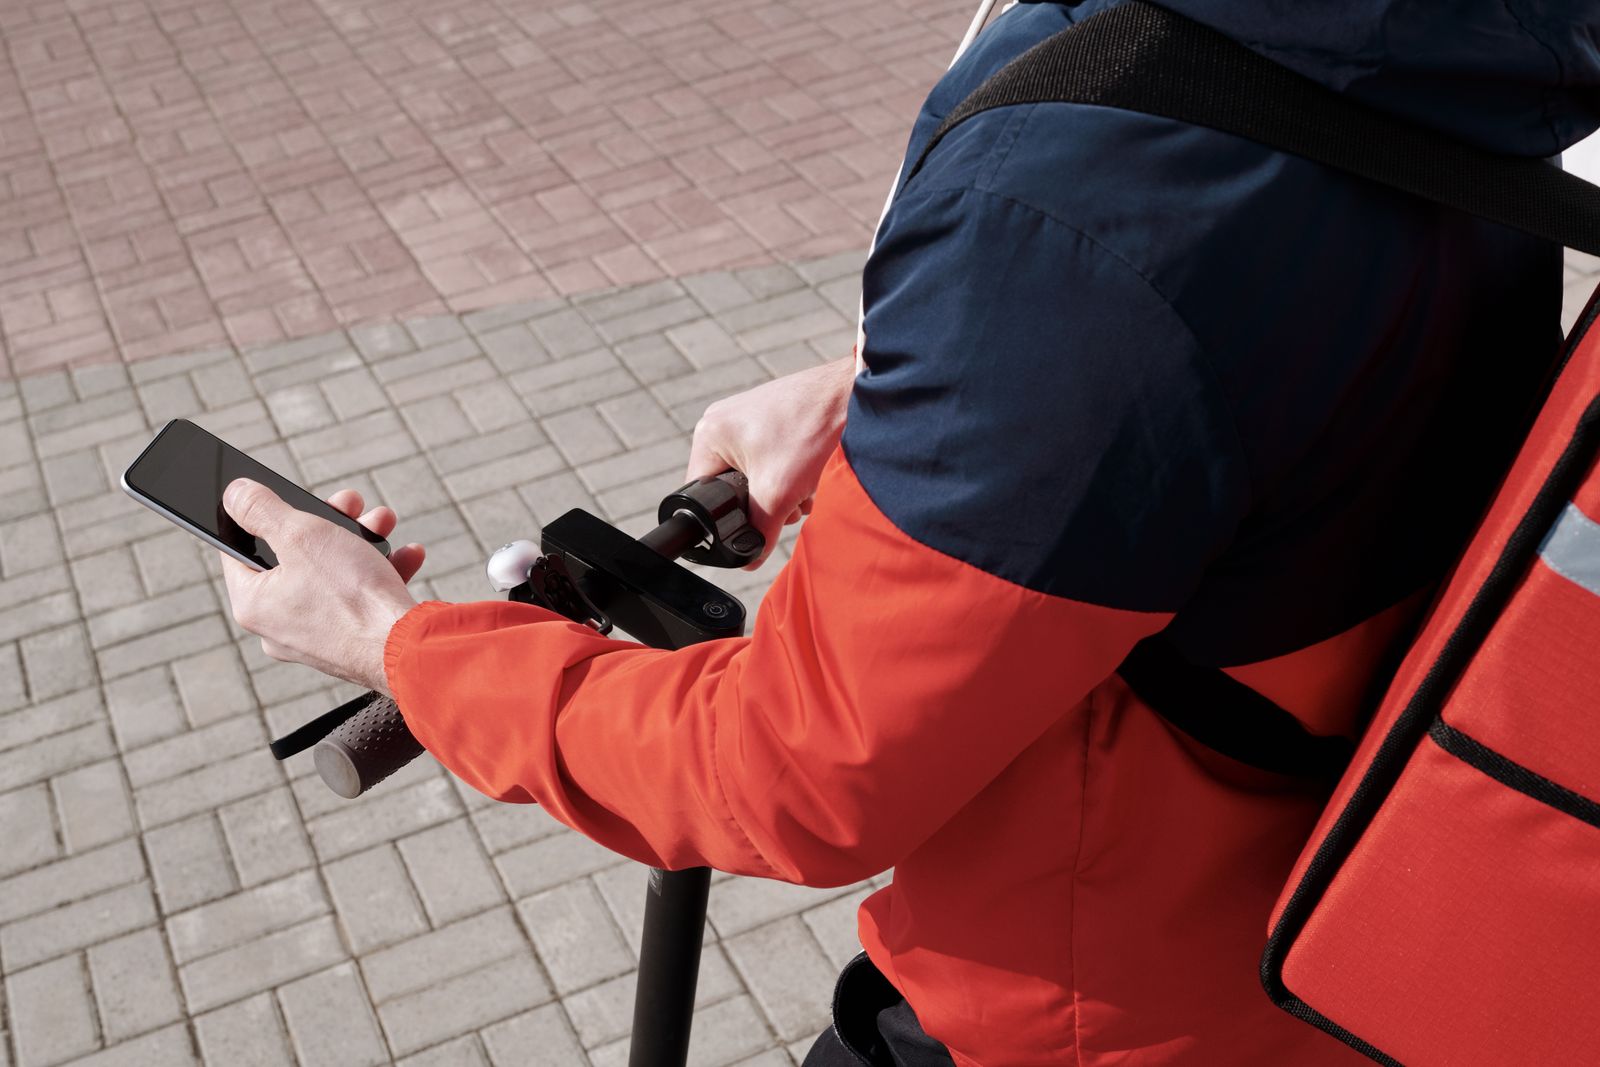
Meituan’s courier network deploys more than 5 million riders at peak periods, structured in tiers from full-time contracted “blue knights” handling high-volume urban routes to flexible crowd-sourced riders managing demand surges. AI routing has reduced average delivery time to approximately 28 minutes — now the benchmark against which all Chinese delivery platforms compete.
The merchant density of this network is the second structural barrier Western entrants face. In Tier 1 cities like Beijing and Shanghai, virtually every restaurant, pharmacy, and convenience store is connected to Meituan. Opening a competitor app means a materially smaller selection — a decisive friction that has kept Meituan’s market share at roughly 67% of China’s food delivery market by order volume as of early 2026, with Alibaba-owned Ele.me at approximately 26%. Despite Alibaba’s resources and Taobao distribution advantages, it has not closed the gap.
Why Western Platforms Keep Failing: Three Structural Gaps
Consumer trust in cross-category use. Chinese consumers have been conditioned over fifteen years to trust super-apps with their full consumer stack — payments, identity, services, and social recommendations. This trust was built partly by WeChat’s dominance in messaging and payments, a platform deeply integrated with Meituan’s ordering flow. Western consumers remain app-specific in behavior, keeping delivery, discovery, and booking tools siloed.
Merchant operational dependence. Meituan’s merchant tools — inventory management, sales analytics, promotional access, and the Dianping review platform — have made the platform an operational backbone for millions of small businesses. Leaving Meituan is not merely removing one delivery channel; it means disconnecting from the primary customer acquisition, reputation management, and operations software that many small merchants rely on daily. This lock-in is qualitatively different from what DoorDash or Deliveroo offer their restaurant partners.
Unit economics anchored by last-mile labor costs. Meituan’s delivery efficiency is partly a function of China’s labor cost structure. Average courier earnings in Tier 1 cities run approximately RMB 6,000-8,000 per month (USD 830-1,100 at current rates) for full-time riders. Replicating the 28-minute delivery promise in London, New York, or Berlin — where gig labor rates run three to five times higher — requires a fundamentally different model. Western platforms have responded with dark stores and robotic delivery pilots, but none has yet reached simultaneous parity on speed, cost, and selection.
Grocery and Instant Retail: The Next Expansion
Meituan’s most strategically significant current investment is Xiaoxiangchao, its instant retail warehouse network. As of mid-2026, Meituan operates more than 10,000 mini-fulfillment centers — small dark stores embedded in residential neighborhoods — designed to enable 10-to-30-minute delivery of grocery and household items.
This moves Meituan into direct competition with traditional grocery retail and the broader consumer goods market. JD.com and Alibaba have equivalent programs, but Meituan’s courier density gives it a structural speed advantage. European quick-commerce startups including Getir, Gopuff, and Flink have studied the Xiaoxiangchao model, though none has replicated the order volume density that makes the Chinese version profitable at scale.
What This Means for Foreign Businesses in China
For foreign companies entering the Chinese market, Meituan is both a distribution channel and a competitive constraint. A restaurant chain, hotel brand, or pharmacy group entering China must treat Meituan as a mandatory partner — it controls consumer discovery and local service fulfillment in a way no single Western platform does at home. Negotiating favorable commission rates (typically 15-23% of food delivery order value) requires merchant scale and brand recognition. Most foreign entrants accept standard terms initially and renegotiate from a position of demonstrated volume.
For a policy reference point, China’s National Development and Reform Commission has published platform economy governance guidelines addressing the balance between innovation and market competition — an evolving framework relevant to any business building on Meituan’s infrastructure. The US Federal Trade Commission’s analysis of platform market dynamics provides a useful comparative lens for executives navigating both regulatory environments. For Chinese regulatory context, the State Council’s Guidelines on Platform Economy Development outline the operating parameters that shape Meituan’s governance obligations.
The Strategic Lesson
Wang Xing’s approach to building Meituan encodes principles that recur across China’s most successful technology companies: willingness to operate at structurally low margins for a decade in pursuit of scale and data advantages; integration of offline and online service delivery to create physical network effects; and using platform economics not merely to intermediate transactions but to become operationally indispensable to both merchants and consumers.
These are not uniquely Chinese insights, but they are executed in China at a speed and scale difficult to match in markets with higher labor costs, stronger platform regulation, and more fragmented consumer digital behavior. Meituan is not just a delivery app. It is one of the most sophisticated demonstrations of what a local services operating system looks like when executed at national scale — and a benchmark that continues to raise the standard for what platform businesses can aspire to build globally.
For broader context on China’s on-demand economy, see China’s Platform Economy: How Didi, Ele.me, and the On-Demand Giants Rewired Urban Commerce. On the payment infrastructure underpinning Meituan’s transactions, read WeChat Pay and Alipay: How China’s Mobile Payment Duopoly Is Reshaping Global Fintech Strategy. For the investor and competitive context behind Meituan’s growth, our analysis of Tencent: Beyond WeChat and Meituan’s $200 Billion Business Model provides essential background.