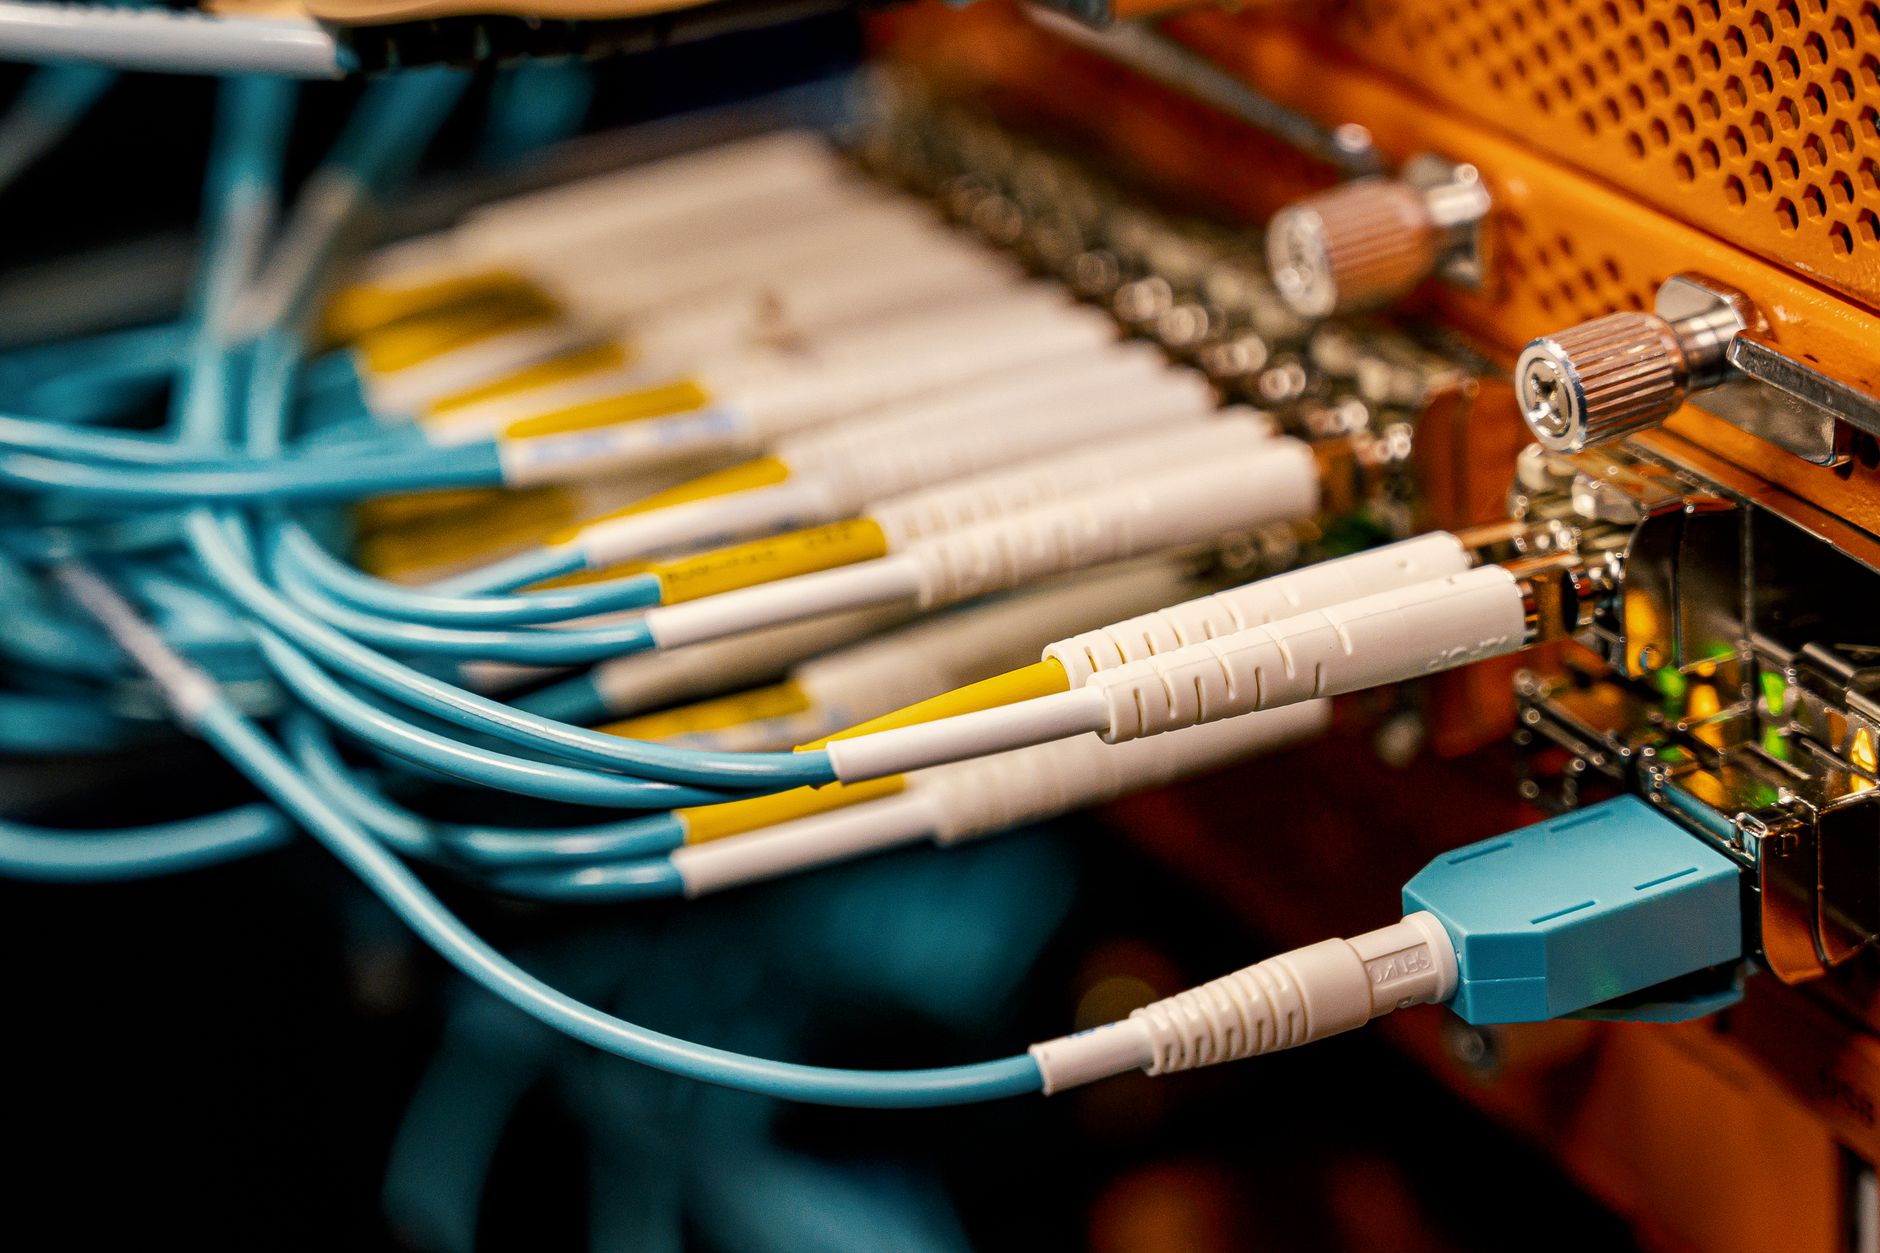
When you stream a video, send a business email, or route a payment across the Pacific, there is a reasonable chance the signal travels through a fiber optic cable manufactured in Wuhan. That is not coincidence. It is the result of a deliberate, decades-long industrial strategy that turned a landlocked Chinese city into the undisputed capital of the world’s fiber optic and optoelectronics industry.
China now produces approximately 60 percent of the world’s optical fiber and cable. Its two largest manufacturers, YOFC (Yangtze Optical Fibre and Cable) and FiberHome Technologies, together dominate global output. Both are headquartered in Wuhan, Hubei Province, and both trace their origins to a government-backed research institute established there in the 1970s. Understanding how this happened matters for every executive sourcing telecom infrastructure, investing in broadband, or navigating the geopolitics of global connectivity.
The Origin: A Research Institute That Became an Industry
The story begins not in a factory but in a laboratory. In 1974, the Chinese government established the Wuhan Research Institute of Posts and Telecommunications (WRI) in the city’s East Lake High-Tech Development Zone, later branded as “China’s Optics Valley” (光谷, Guanggu). WRI was tasked with developing fiber optic communication technology at a time when most of the world was still transitioning from copper wire networks.
The institute produced China’s first homegrown optical fiber in 1976. By the early 1990s, China had begun commercializing fiber optic cable production, and Wuhan was the geographic center. WRI spun out two industry-defining companies: FiberHome Technologies in 1999, and YOFC as a joint venture between WRI, Dutch cable company Draka, and Yangtze Investment. That structure gave YOFC early access to Western manufacturing know-how while Chinese institutions retained operational control.
Two Giants and a Complete Ecosystem
YOFC is today one of the world’s three largest fiber optic cable manufacturers, alongside Corning (USA) and Prysmian (Italy). Listed on both the Shanghai and Hong Kong stock exchanges, YOFC reported revenues exceeding RMB 15 billion in recent years. The company operates manufacturing facilities across China as well as plants in South Africa, the Netherlands, and Indonesia, serving customers in more than 80 countries.
FiberHome Technologies, a subsidiary of WRI, positions itself as an end-to-end telecommunications solutions provider. It does not merely supply cable; it designs and deploys entire network systems, including optical transmission equipment, data communication products, and smart city infrastructure. FiberHome’s revenues exceed RMB 20 billion. The company serves China’s three state-owned carriers, China Mobile, China Unicom, and China Telecom, and has signed infrastructure contracts across Africa, Southeast Asia, and Latin America under the Belt and Road Initiative framework.
Around these two anchors, Wuhan’s Optics Valley has cultivated a cluster of more than 1,300 optoelectronics enterprises. These include laser manufacturers, optical component makers, photonic chip designers, and specialty glass producers. The zone generates annual output value exceeding RMB 500 billion, making it one of China’s highest-concentration high-tech industrial clusters.
Why Wuhan? The Geographic and Policy Logic
Wuhan’s emergence as the optoelectronics capital rested on three converging advantages. First, the inherited WRI research base created a pipeline of trained engineers and proprietary IP. Huazhong University of Science and Technology (HUST) reinforced this with one of China’s most respected optics and electronics programs, feeding talent directly into the local industry.
Second, Wuhan sits at China’s geographic center, intersected by major rail and river freight routes. The Yangtze River provides bulk transport for raw materials, and the city’s position equidistant from coastal export hubs and inland markets makes logistics economics favorable.
Third, municipal and provincial governments treated the cluster as a strategic priority. Preferential land pricing, tax incentives, and direct research investment compounded over decades. The Wuhan East Lake Comprehensive Free Trade Zone, approved in 2017, further reduced barriers for international partnerships and technology licensing.
The 5G Acceleration and Its Global Implications
China’s domestic 5G buildout, which deployed more than 3.6 million base stations by 2025 according to China’s Ministry of Industry and Information Technology, drove an extraordinary surge in fiber optic cable demand. Each 5G base station requires multiple fiber strands for fronthaul, midhaul, and backhaul connectivity, driving orders of hundreds of thousands of cable kilometers annually during peak deployment years.
This domestic demand gave YOFC and FiberHome enormous manufacturing scale advantages. High production volumes reduced per-unit costs, enabling aggressive international pricing. Industry analysts have estimated that Chinese fiber optic cable can be priced 20 to 40 percent below equivalent European-manufactured products during peak demand cycles. For foreign telecommunications companies and national broadband operators sourcing fiber infrastructure, the competitiveness of Chinese suppliers became difficult to ignore.
The 5G connection also runs through Wuhan’s broader tech ecosystem. As covered in our analysis of China’s 5G infrastructure rollout, Huawei and ZTE supply the radio equipment that sits at the network’s top layer while Wuhan’s fiber specialists supply the physical transmission backbone beneath it. The two industries are deeply complementary.
Supply Chain Risk and What Western Buyers Must Know
For procurement managers and infrastructure investors in the United States and Europe, China’s fiber optic dominance raises questions that go beyond price. Several issues warrant careful attention.
First, YOFC’s ownership structure includes Draka (now part of Prysmian Group), meaning Western capital is partially entangled in one of China’s flagship optoelectronics producers. This complicates any binary framing of “Chinese” versus “Western” supply chains.
Second, FiberHome’s deep ties to China’s state telecoms carriers and its Belt and Road infrastructure role have drawn scrutiny in some Western procurement reviews. The U.S. Federal Communications Commission has designated certain Chinese telecoms equipment as presenting national security concerns, though fiber optic cable itself, as a passive transmission medium, has generally remained outside these restrictions. Buyers should nonetheless conduct thorough due diligence given the evolving regulatory environment. Our analysis of the ZTE sanctions case illustrates how quickly the regulatory landscape in this sector can shift.
Third, concentration of global fiber optic production in Wuhan creates supply chain resilience questions. The COVID-19 pandemic, which shut Wuhan for 76 days in early 2020, exposed how this geographic concentration can ripple through global telecoms supply chains. The U.S. Department of Commerce has noted fiber optic components in its critical supply chain assessments, and there is growing interest in diversifying production to India, Vietnam, and the United States. The National Telecommunications and Information Administration (NTIA) has published supply chain risk guidance relevant to fiber optic infrastructure procurement under its Broadband Infrastructure programs, available at ntia.gov.
Where the Bilateral Opportunity Is Real
Despite geopolitical complexity, substantial bilateral opportunity exists. The $42.45 billion BEAD Program is driving record US fiber optic demand, and American network operators seeking cost-competitive supply cannot ignore the world’s most efficient production base. YOFC’s Prysmian partnership demonstrates that commercially structured joint ventures can satisfy both economic and governance requirements.
Chinese manufacturers also have genuine incentives to build credibility in Western markets through third-country manufacturing, joint ventures, and technology licensing deals that satisfy local content or security requirements.
Wuhan’s research institutions present collaboration opportunities in photonic chip development, a field where China remains behind leading US and Taiwanese producers. Companies like Intel and Coherent have engaged in research partnerships with Chinese universities on photonic integration. As China pursues semiconductor self-sufficiency, photonic chips represent an area where international technology transfer can be structured in ways less politically fraught than mainstream silicon semiconductors.
Wuhan in China’s Tech Geography
Wuhan’s Optics Valley occupies a specific, underappreciated niche in China’s industrial map. Shenzhen dominates consumer electronics hardware. Beijing concentrates internet platforms and AI research. Shanghai leads in financial services and biotech. Wuhan, meanwhile, owns a less glamorous but critically important layer: the physical transmission medium that makes all of the above possible at global scale.
The broader context of Central China’s industrial rise provides essential background for executives looking at Wuhan beyond fiber optics. Optoelectronics remains its most globally consequential claim, and the Optics Valley model, built on research institutions, patient government investment, strategic foreign partnerships, and domestic demand-driven scale, is a blueprint China has replicated across solar panels, semiconductor packaging, and industrial robotics.
For business leaders on both sides of the Pacific, the practical implication is straightforward: Chinese dominance in fiber optic cable is structural, not cyclical. Corning holds its ground through premium specialty applications and submarine cable technology. The productive response for most Western companies is not to pretend the dominance does not exist, but to engage with it clearly, with appropriate due diligence, contractual protections, and geopolitical risk monitoring built into every sourcing relationship.